GLOBAL SUPPLY CHAIN PRESSURES EASE IN JULY, BUT SHORTAGES PERSIST AHEAD OF RENEWED STRAIT OF HORMUZ DISRUPTION: GEP GLOBAL SUPPLY CHAIN VOLATILITY INDEX
- Demand for intermediate goods and raw materials stagnates in July as manufacturers reduced safety-stock building
- Supply shortages remained elevated, leaving production vulnerable to fresh geopolitical shocks
- Asia and North America continued to lead global manufacturing demand, while Europe continues to lag
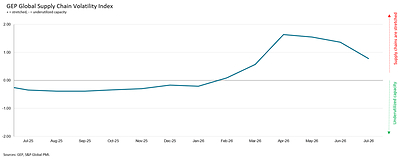
CLARK, N.J., Aug. 12, 2026 /PRNewswire/ -- GEP Global Supply Chain Volatility Index — a leading indicator tracking demand conditions, shortages, transportation costs, inventories and backlogs, based on a monthly survey of 27,000 businesses — showed global supply chain pressures eased in July as manufacturers reduced precautionary stockpiling and transportation pressures moderated. However, supply shortages remained elevated and production backlogs continued to build, indicating supply chains had yet to fully recover before the renewed disruption in the Strait of Hormuz.
The survey was mostly conducted before the latest escalation in the Middle East and renewed disruption to shipping through the Strait of Hormuz, providing a snapshot of global supply chains immediately before energy prices and geopolitical uncertainty increased again.
Manufacturers scaled back safety-stock building in July following a three-and-a-half-year peak in the second quarter of 2026, suggesting businesses believed supply risks were beginning to ease. Transportation costs also moderated, helping drive the overall improvement in global supply chain conditions.
Despite the easing, reports of critical items in short supply remained elevated globally, while manufacturers continued reporting rising production backlogs caused by missing materials and components. This indicates supply bottlenecks remain unresolved and could worsen if geopolitical tensions persist.
Demand for raw materials and commodities remained strongest across Asia and North America, where manufacturers continued purchasing inputs at a significantly faster pace than other major regions. Europe, by contrast, remained comparatively subdued, reflecting weaker manufacturing order books and lower inventory building.
Interpreting the data:
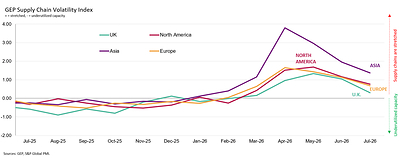
Index > 0, supply chain capacity is being stretched. The further above 0, the more stretched supply chains are.
Index < 0, supply chain capacity is being underutilized. The further below 0, the more underutilized supply chains are.
JULY 2026 REGIONAL KEY FINDINGS
- ASIA: Index decreased to 1.37, from 1.95, its lowest reading since March. Asian factory purchasing activity slowed sharply in July, driven by China.
- NORTH AMERICA: Index fell to 0.76, from 1.17, pointing to a further easing of supply chain pressures faced by North American manufacturers.
- EUROPE: Index declines to 0.68, from 1.13, its lowest level since March. Demand for manufacturing inputs shrank further, indicating factory retrenchment across the continent.
- U.K.: Sharp reduction in the index to 0.30, from 1.05 as U.K. manufacturers rapidly reduced their procurement activity and ran down their stocks aggressively.
JULY 2026 KEY FINDINGS
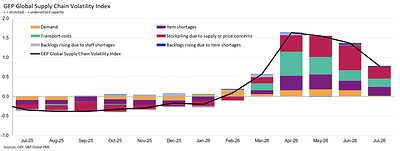
- DEMAND: July data indicated a slowdown in factory purchasing volumes. The index's demand component was its weakest in the year-to-date, driven principally by China and, to a lesser extent, the U.S. The data suggest that the stockpiling-driven boost to demand has faded at the start of the third quarter.
- INVENTORIES: Reports of global manufacturers stockpiling raw materials and intermediate products due to price or supply concerns fell for the first time since January, indicating that procurement leaders ran down the inventories they had built up since the Middle East war began.
- MATERIAL SHORTAGES: The items in short supply indicator fell only fractionally in July, indicating a limited improvement in the availability of critical manufacturing inputs. Overall, supply shortages remained high by historical standards.
- LABOR SHORTAGES: Manufacturers' reports of backlogs rising due to staff shortages remained anchored, signaling that labor was not a hindrance to capacity utilization during July.
- TRANSPORTATION: The global transportation cost indicator fell again in July, reaching its lowest level since March. That said, data were principally collected prior to global oil prices surging towards the tail-end of the month.
For more information, visit www.gep.com/volatility.
Note: Full historical data dating back to January 2005 is available for subscription. Please contact economics@spglobal.com.
The next release of the GEP Global Supply Chain Volatility Index will be 8 a.m. ET, Sep. 11, 2026.
About the GEP Global Supply Chain Volatility Index
The GEP Global Supply Chain Volatility Index is produced by S&P Global and GEP. It is derived from S&P Global's PMI® surveys, sent to companies in over 40 countries, totaling around 27,000 companies. The headline figure is a weighted sum of six sub-indices derived from PMI data, PMI Comments Trackers and PMI Commodity Price & Supply Indicators compiled by S&P Global.
- A value above 0 indicates that supply chain capacity is being stretched and supply chain volatility is increasing. The further above 0, the greater the extent to which capacity is being stretched.
- A value below 0 indicates that supply chain capacity is being underutilized, reducing supply chain volatility. The further below 0, the greater the extent to which capacity is being underutilized.
A Supply Chain Volatility Index is also published at a regional level for Europe, Asia, North America and the U.K. For more information about the methodology, click here.
Media Contacts
Derek Creevey
Director, Public Relations
GEP
Phone: +1 646-276-4579
Email: derek.creevey@gep.com
Joe Hayes
Senior Principal Economist
S&P Global Market Intelligence
Phone: +44-1344-328-099
Email: joe.hayes@spglobal.com
S&P Global Market Intelligence
Corporate Communications
Email: Press.mi@spglobal.com
 View original content to download multimedia:https://www.prnewswire.co.uk/news-releases/global-supply-chain-pressures-ease-in-july-but-shortages-persist-ahead-of-renewed-strait-of-hormuz-disruption-gep-global-supply-chain-volatility-index-302849802.html